For family law solicitors in England & Wales
What can your client realistically borrow?
An independent mortgage capacity report for financial remedy proceedings, with every figure and assumption set out, delivered within two working days of receiving all the information needed.
Opens a pre-addressed email, or write to luke@mortgagereports.org
Mortgage capacity assessment
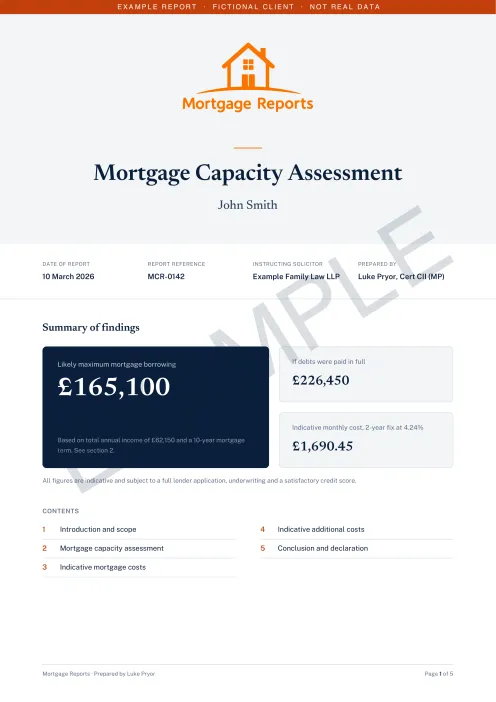
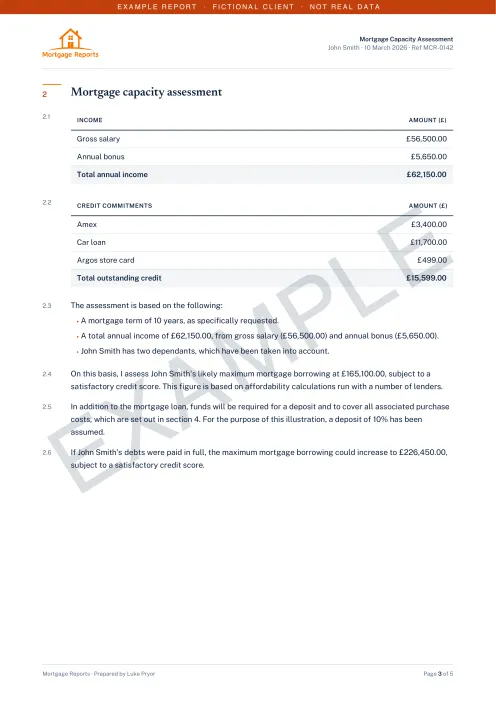
Example report- Total annual income
- £62,150
- Outstanding credit commitments
- £15,599
- Mortgage term
- 10 years, to age 67
- Dependants
- 2
Figures from the sample report. Indicative only; lenders change their criteria regularly.
- The headline figure, calculated from your client's income, commitments and circumstances, with each assumption stated.
- Borrowing capacity if debts are repaid, shown wherever your client has outstanding credit.
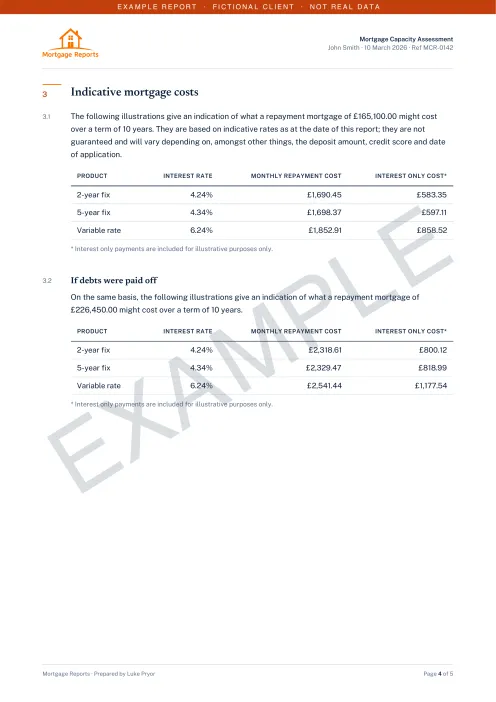
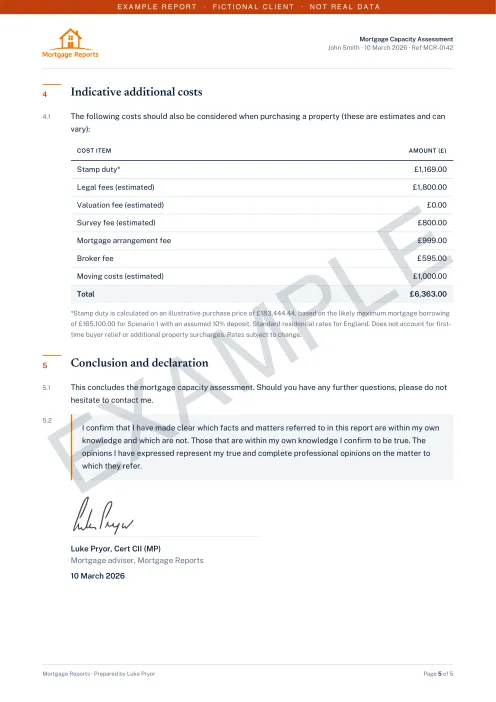
- Monthly costs at indicative fixed and variable rates, together with purchase costs including stamp duty.
- £195Single report, fixed fee
- £295Joint report, fixed fee
- 2 working daysFrom receiving all the information needed
- No credit searchNo record on your client's credit file
The report
A concise report addressing the borrowing questions central to financial remedy proceedings, prepared for disclosure to the other party and the court.
- Maximum borrowing capacityA realistic figure based on current lending criteria, rather than a best-case estimate.
- Capacity if debts are repaidShowing whether clearing credit commitments from the settlement would materially change the position.
- Monthly mortgage costsAt indicative 2-year fixed, 5-year fixed and variable rates, on repayment and interest-only bases.
- Associated purchase costsStamp duty, legal, valuation, survey and arrangement fees, and removal costs.
- Stated assumptionsTerm, retirement age, income sources, dependants and deposit, each set out so that it can be scrutinised.
- Signed conclusion and declarationConfirming which facts are within the author's own knowledge and that the opinions expressed are true and complete.
When a report assists
Borrowing capacity underpins most questions of housing need. An independent figure obtained early can narrow the issues between the parties.
Disputed housing needs
Where a party seeks a greater share of the equity in order to rehouse, the report establishes what they could reasonably raise by way of mortgage.
Contested borrowing capacity
Where a party asserts that they cannot obtain a mortgage, an assessment based on their actual income and commitments tests that position objectively.
Preparation for an FDR
An evidenced borrowing figure provides a sound basis for settlement proposals.
Debts, maintenance and alternatives
The report shows the effect of repaying debts and can model alternative scenarios, such as a different term or level of income.
Process
All correspondence is conducted through you, as the instructing solicitor, by email.
-
Instruction
Email your instruction with the client's name, whether a single or joint report is required, your reference and any hearing date. The Instruct button prepares the email for you.
-
Client information form
I send you a short form to complete with your client, covering income, credit commitments, dependants and any purchase plans.
-
Return of the form
Return the completed form by email.
-
Report
The signed report is sent to you by email within two working days of receiving all the information required, with the invoice addressed to your firm.
Fees
Fixed fees, invoiced directly to your firm. VAT is not applicable.
Single report
Assessment of one party's borrowing capacity
£195no VAT
- Likely maximum borrowing
- Borrowing with debts cleared, where relevant
- Monthly costs at fixed and variable rates
- Purchase costs including stamp duty
- Delivered within 2 working days
Joint report
Assessment of two applicants borrowing jointly
£295no VAT
- Likely maximum joint borrowing
- Both incomes and commitments assessed together
- Monthly costs at fixed and variable rates
- Purchase costs including stamp duty
- Delivered within 2 working days
Additional scenarios £50 eachInvoiced directly to your firmNo VAT applicable
About the author
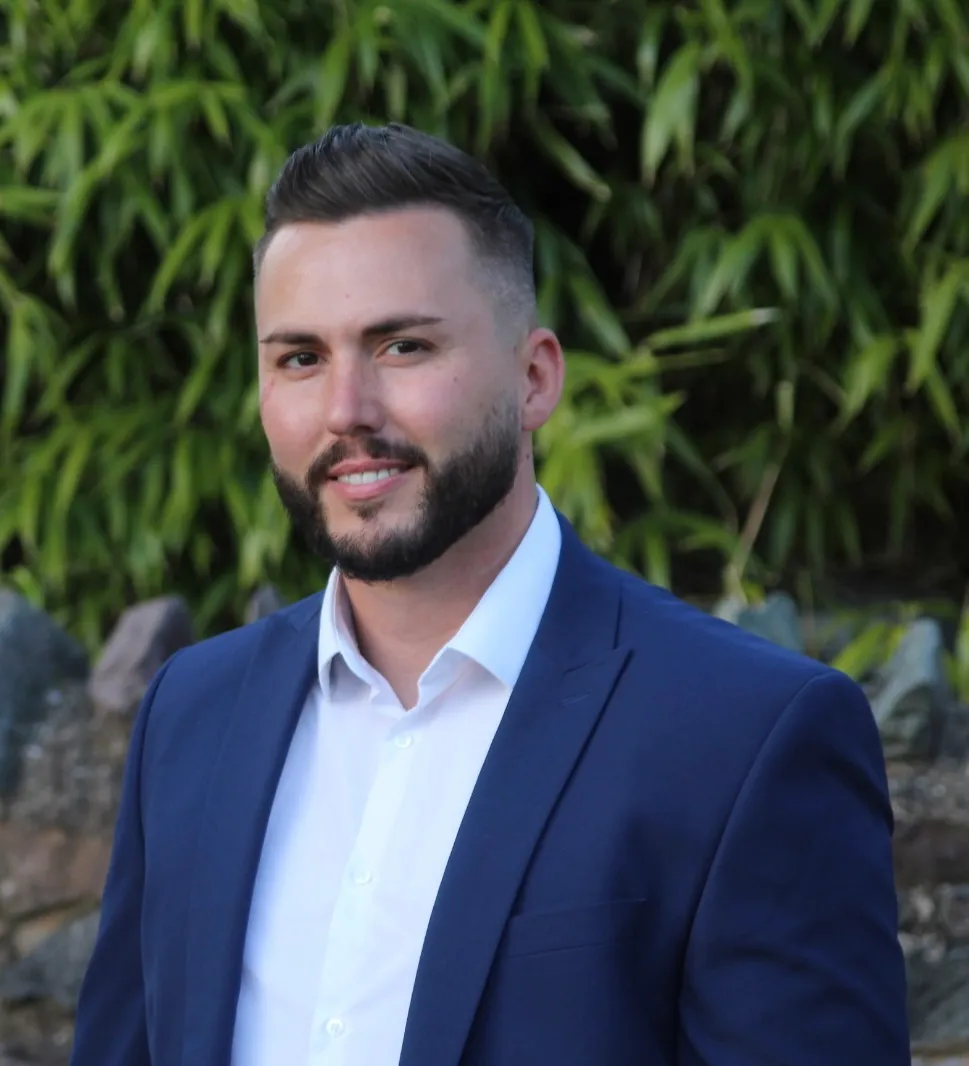
Luke Pryor
Mortgage adviser, Mortgage Reports
I am a mortgage adviser specialising in mortgage capacity reports for family proceedings. Every report is prepared by me personally from the information provided, and assessed against current lending criteria across the market.
Reports are written for solicitors and the court: figures first, assumptions stated clearly, and no product recommendations.
Outside work, I am a competitive weightlifter and a keen hill walker.
Frequently asked questions
Who may instruct a report?
Instructions are accepted from solicitors only. I take instructions from the firm acting for the client, correspond with that firm throughout and invoice it directly.
What information is required from my client?
The details requested on the client information form: income (employment, self-employment, benefits and maintenance), credit commitments and their monthly payments, dependants and, where known, purchase plans. The form is sent to you on instruction.
Does the assessment affect my client's credit file?
No. No credit search, underwriting or credit scoring is carried out, so nothing is recorded on your client's credit file.
Is the borrowing figure guaranteed?
No, and the report states this. It is an indication of what could likely be borrowed, based on the client's circumstances and lending criteria at the date of the report. As lenders change their criteria regularly, the amount available at the point of application may be higher or lower.
Does the report recommend a lender or product?
No. The report assesses borrowing capacity only. The rates shown are indicative and are used solely to illustrate monthly costs.
Can additional scenarios be modelled?
Yes. Where your client has outstanding debts, the report already shows borrowing capacity with those debts repaid. Further scenarios, such as a different term or a change in income, are charged at £50 each and should be specified when instructing.
How is my client's information handled?
It is used solely to prepare the report, retained for six years after the report is issued and then deleted. Further detail is set out in the privacy notice.
Instruct a report
Instructing a report
The button below opens a pre-addressed email in your mail application. Complete the details and send it, and I will reply with the client information form.
Alternatively, email luke@mortgagereports.org directly.